Most people buy their flat in Pune with a home loan. Before you pay a booking amount, you should know three numbers: how much the bank will lend you, how much you must pay yourself as a down payment, and what your monthly EMI will be. This guide explains each one with simple tables and real examples from the projects on the Mappingg live map.
How much down payment do you need?
Banks and housing finance companies don’t fund the full price of a flat. RBI rules cap the loan-to-value (LTV) ratio, so you pay the rest yourself:
| Loan amount | Maximum loan (LTV) | Your minimum down payment |
|---|---|---|
| Up to ₹30 Lacs | 90% | 10% |
| ₹30 Lacs – ₹75 Lacs | 80% | 20% |
| Above ₹75 Lacs | 75% | 25% |
Two things catch buyers out. First, the LTV is worked out on the property’s value, which generally excludes stamp duty and registration, so you pay those from savings too. Second, a lender can approve less than the maximum based on your income and credit score.
Home loan EMI table
Your EMI depends on the loan amount, the interest rate and the tenure. Here is the EMI at an illustrative rate of 8.5% a year:
| Loan amount | 15 years | 20 years | 25 years | 30 years |
|---|---|---|---|---|
| ₹30 Lacs | ₹29,542 | ₹26,035 | ₹24,157 | ₹23,067 |
| ₹50 Lacs | ₹49,237 | ₹43,391 | ₹40,261 | ₹38,446 |
| ₹60 Lacs | ₹59,084 | ₹52,069 | ₹48,314 | ₹46,135 |
| ₹75 Lacs | ₹73,855 | ₹65,087 | ₹60,392 | ₹57,669 |
| ₹1 Crore | ₹98,474 | ₹86,782 | ₹80,523 | ₹76,891 |
| ₹1.5 Crore | ₹1,47,711 | ₹1,30,173 | ₹1,20,784 | ₹1,15,337 |
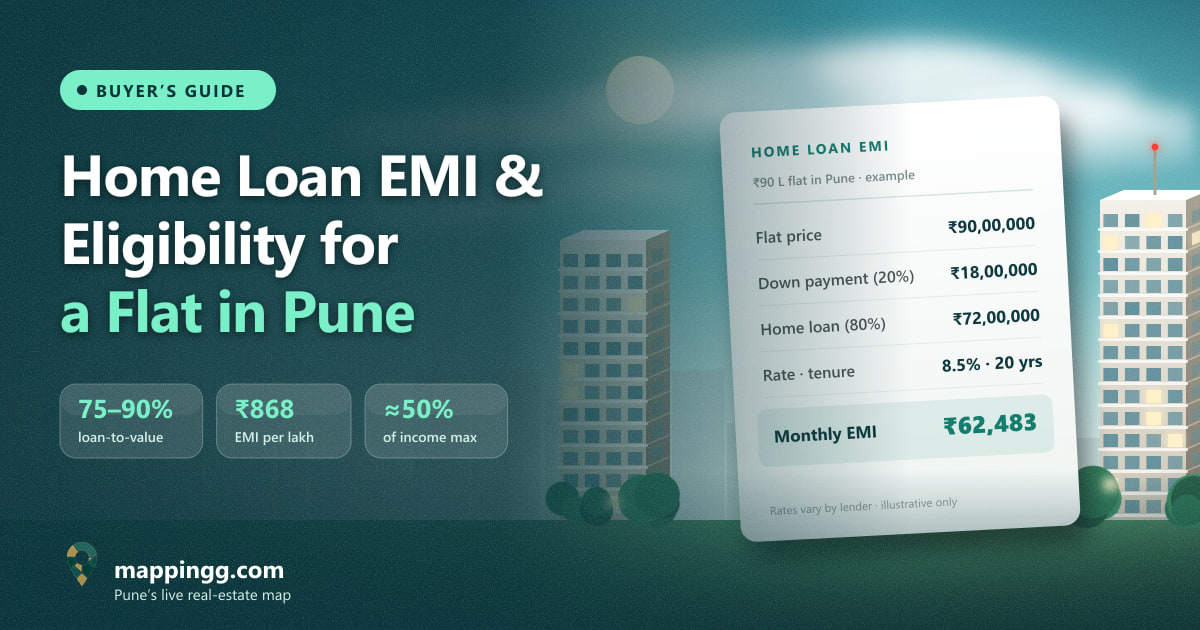
A quick rule of thumb: at 8.5% over 20 years, every ₹1 Lac of loan costs about ₹868 a month. Actual rates depend on the lender, your credit score and the RBI repo rate, so check current offers before you decide.
How the interest rate changes your EMI
On a ₹50 Lacs loan over 20 years, the EMI is ₹41,822 at 8%, ₹43,391 at 8.5%, ₹44,986 at 9% and ₹46,607 at 9.5%. Even half a percent makes a difference of about ₹1,600 a month, or nearly ₹4 Lacs over the life of the loan, so it pays to compare lenders.
The true cost of a longer tenure
A longer tenure lowers your EMI but raises the total interest. On a ₹50 Lacs loan at 8.5% for 20 years, you repay about ₹1.04 Cr in all, of which about ₹54 Lacs is interest. Making part-prepayments whenever you get a bonus is the simplest way to cut that.
How much home loan can you get on your salary?
Lenders usually let your total EMIs (including car loans and personal loans) take up to about 50–60% of your net monthly income. This is called the FOIR (fixed obligations to income ratio). For example, with a take-home salary of ₹1 Lac a month and no other loans, a 50% FOIR allows an EMI of ₹50,000, which supports a loan of about ₹57.6 Lacs over 20 years at 8.5%.
Ways to increase your eligibility:
- Add a co-applicant, such as an earning spouse or parent, so both incomes are counted.
- Close small loans and card dues before you apply, to free up FOIR.
- Choose a longer tenure, if your age allows it.
- Keep your credit score high. A score above 750 usually gets you the best rates.
Example: the loan for real Pune flats
Here is what it would take to buy some of the projects on our map at their starting price, with the maximum loan, a 20-year tenure and 8.5% interest:
| Project | Starting price | Down payment | Loan | EMI (20 yrs) |
|---|---|---|---|---|
| Everlyn, Hinjewadi | ₹82 Lacs | ₹16.4 Lacs | ₹65.6 Lacs | ₹56,929 |
| KP SUPERNOVA, NIBM | ₹90 Lacs | ₹18 Lacs | ₹72 Lacs | ₹62,483 |
| Ravima Newtown, Mundhwa | ₹98 Lacs | ₹24.5 Lacs | ₹73.5 Lacs | ₹63,785 |
| Osian Almanova, Mundhwa | ₹1.55 Cr | ₹38.75 Lacs | ₹1.16 Cr | ₹1,00,884 |
Down payments exclude stamp duty, registration and GST. At a 50% FOIR, these EMIs need a take-home income of roughly ₹1.14 Lacs, ₹1.25 Lacs, ₹1.28 Lacs and ₹2 Lacs a month respectively.
Notice that Ravima Newtown needs a much larger down payment than KP Supernova even though the price is only ₹8 Lacs higher: at 80% the loan would cross ₹75 Lacs, so the 75% limit applies. Looking for homes in a lower band? See our guide to flats under ₹1 crore in Pune.
Home loans for under-construction flats
- Staged disbursement: the bank pays the developer in instalments as construction progresses, not all at once.
- Pre-EMI: until the full loan is disbursed, you can pay interest only on the amount released so far (pre-EMI), or start the full EMI straight away. Pre-EMI feels lighter, but it doesn’t reduce your principal.
- Approved projects: banks often pre-approve large MahaRERA-registered projects, which makes the loan faster. Always check the MahaRERA number yourself as well.
- Rent plus EMI: if you are renting, budget for both until possession. Our guide to ready-to-move vs under-construction flats explains the trade-off.
Documents you will need
- KYC: PAN card and Aadhaar or passport for every applicant.
- Income proof (salaried): the last 3–6 months’ salary slips, Form 16 and 6–12 months’ bank statements.
- Income proof (self-employed): 2–3 years of income tax returns with computation, audited financials and business bank statements.
- Property papers: the allotment letter or agreement for sale, the developer’s MahaRERA certificate, approved plans and the payment receipts.
- For a resale flat: the chain of title documents, the society NOC and the occupancy certificate.
Tax benefits on a home loan
Under the old tax regime, you can usually claim up to ₹2 Lacs a year of interest on a self-occupied home, and up to ₹1.5 Lacs of principal repayment within the overall 80C-style limit. Co-owners who are also co-borrowers can each claim their share. The new tax regime doesn’t allow these deductions for a self-occupied home. Tax law and section numbers have changed recently, so confirm what applies to you with a tax adviser.
Tips to get the best home loan deal
- Get a sanction letter before you book, so you know your exact budget.
- Compare at least three lenders on the interest rate, processing fee and prepayment terms. Floating-rate loans to individuals carry no prepayment penalty.
- Plan the extra costs. Stamp duty, registration and GST are paid from your own pocket. See our guide to stamp duty and hidden costs.
- Remember the 1% TDS on flats worth ₹50 Lacs or more, deducted from every payment to the developer, including bank disbursements.
- Keep an emergency fund of at least six months of EMIs.
FAQs: Home loans in Pune
How much home loan can I get on a ₹1 lakh salary?
With no other loans, roughly ₹55–60 Lacs over 20 years at about 8.5%, depending on the lender’s FOIR limit and your credit score. Adding an earning co-applicant can increase this.
What is the EMI on a ₹50 lakh home loan?
About ₹43,391 a month over 20 years at 8.5%, or ₹38,446 over 30 years.
Can a bank fund 100% of the flat’s price?
No. You must pay at least 10–25% as a down payment, depending on the loan size, plus stamp duty and registration.
Is it better to choose a shorter or longer tenure?
A shorter tenure saves interest but raises your EMI. Many buyers choose a longer tenure for a comfortable EMI and then prepay whenever they can.
EMIs in this guide are illustrative, at 8.5% a year, and are not an offer of credit. Interest rates, lending rules and tax provisions change, so confirm the details with your lender and a tax adviser. Project prices are as listed on Mappingg in October 2026.